Loading…
Free Excel template
Job work register format in Excel
A free challan-wise register for goods you send to job workers. It works out what is still pending at each vendor, the date it must be back under GST, and which ITC-04 period each challan belongs to.
Download the Excel file
job-work-register.xlsx, 60 KB. Free, no sign-up.
What’s inside
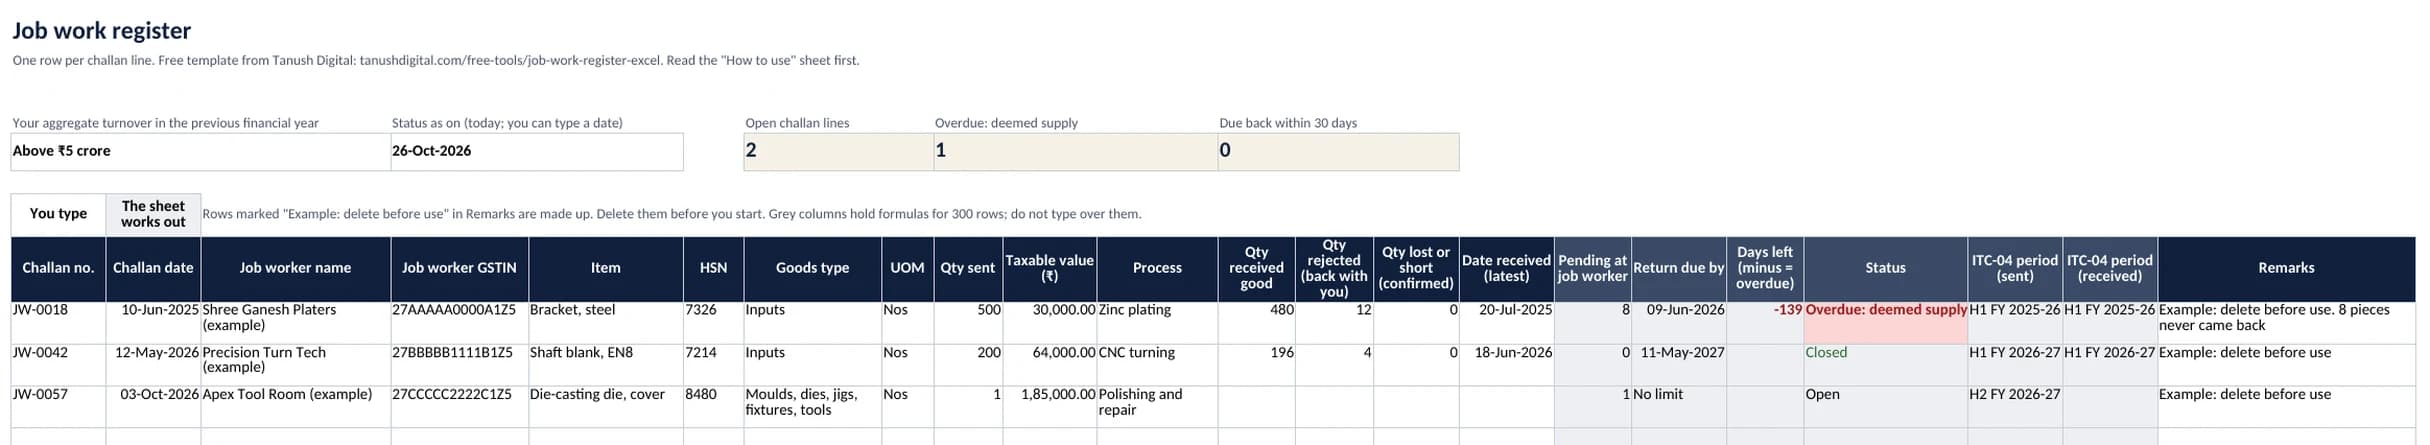
White columns are for you to type. Grey columns hold the formulas, so the sheet works the rest out.
You type
| Column | What it holds |
|---|---|
| Challan no. and challan date | From your job work challan. One row for each item on the challan. |
| Job worker name and GSTIN | GSTIN if the job worker is registered. |
| Item, HSN and UOM | As on the challan. |
| Goods type | A dropdown: Inputs, Capital goods, or Moulds, dies, jigs, fixtures, tools. It sets the time limit. |
| Qty sent and taxable value | As on the challan. |
| Process | Plating, machining, heat treatment and so on. |
| Qty received good, rejected, and lost or short | Rejected pieces are back with you. Enter lost or short only when the job worker confirms it in writing. |
| Date received | The latest date, if the goods come back in lots. |
| Remarks | The job worker's challan numbers, notes for your CA. |
The sheet works out
| Column | What it holds |
|---|---|
| Pending at job worker | Qty sent minus good, rejected, and lost or short. |
| Return due by | The day before the first anniversary of the challan date for inputs, the day before the third anniversary for capital goods (the cautious reading, the same as our ITC-04 calculator; confirm with your accountant), and “No limit” for moulds, dies, jigs, fixtures and tools. |
| Days left | Counted to the “status as on” date at the top, which is today unless you type one. Minus means overdue. |
| Status | Closed when nothing is pending, Open, or “Overdue: deemed supply” when goods are still pending after the due date. |
| ITC-04 period, sent and received | H1 or H2 of the financial year if your turnover was above ₹5 crore, otherwise the year. |
| Counters at the top | Open challan lines, overdue lines, and lines due back within 30 days. |
Also in the file
- A turnover setting at the top: above or up to ₹5 crore in the previous year
- Dropdowns, date checks and a 15-character GSTIN check
- Frozen header row and a filter on every column
- Print setup: A4 landscape, one page wide, header row on every page
- A “How to use” sheet with the time limits, ITC-04 periods and sources
- Formulas filled in for 300 rows
How to use it
- 1Delete the three example rows, then pick your turnover setting at the top.
- 2As goods leave, add a row for every item on the challan: who it went to, what, how many, the value and the process.
- 3When goods come back, fill in the good and rejected quantities and the date. The status updates itself.
- 4Every week, filter Status for “Overdue: deemed supply” and sort Days left, so nothing reaches the limit unnoticed.
- 5At ITC-04 time, filter the period columns: challans sent go by the sent period, goods back by the received period.
Worked example: 500 brackets out for zinc plating
Challan JW-0018 sends 500 steel brackets, as inputs, to a plating shop on 10 June 2025. On 20 July 2025, 480 come back good and 12 are rejected. Turnover is above ₹5 crore. The sheet shows:
| Column | Shows | Because |
|---|---|---|
| Pending at job worker | 8500 − 480 − 12 − 0 | 500 − 480 − 12 − 0 |
| Return due by | 9 June 2026Inputs: within one year of being sent out, read cautiously as the day before the anniversary | Inputs: within one year of being sent out, read cautiously as the day before the anniversary |
| Days left | −139On 26 October 2026, the date is 139 days past | On 26 October 2026, the date is 139 days past |
| Status | Overdue: deemed supplyPieces still pending after the due date | Pieces still pending after the due date |
| ITC-04 period (sent) | H1 FY 2025-26June falls in April to September | June falls in April to September |
Under section 143(3), those 8 brackets are treated as supplied to the plating shop on 10 June 2025. Rule 45(4) says you declare that supply in GSTR-1 and pay the tax with interest. A weekly look at the overdue counter is how you catch it before the year is up.
What it doesn’t do
- It doesn’t file ITC-04 or make the JSON for the GST portal. It tells you which period each line belongs to.
- It doesn’t print challans or raise e-way bills.
- It doesn’t know about extensions. If the Commissioner extends the limit for a challan, type the new date over the formula in that row.
- It keeps one row per challan line, so lots that come back on different dates are added up under the latest date. If the lots fall in two ITC-04 periods, report each in its own period.
- It isn’t your stock record. Material at job workers still has to show in your stock books.
- It isn’t tax advice. Check how a particular case is treated with your CA.
When the register outgrows Excel
ERPNext holds the same flow in one system. A Subcontracting Order names the job worker and their warehouse, a “Send to Subcontractor” stock entry is the challan, and a Subcontracting Receipt books the good and rejected quantities back. With one warehouse per job worker, the stock balance shows what each one holds. The India Compliance app’s GST Job Work Stock Movement report exports the ITC-04 file for tables 4 and 5A.
Standard subcontracting needs a subcontracted item and a BOM for every outside stage, which multiplies item codes. For manufacturers we work with, we built a vendor job-work card and register as a custom Frappe app beside ERPNext:
- A job-work card that tracks each outside step, with no extra item codes
- A job-work challan with the rule 55 details, carrying many products to one vendor
- A vendor receipt for good, rejected and rework pieces, with incoming inspection
- A register per vendor of what was sent, what came back, what is pending and when it is due, with overdue alerts
We look at your challans and vendors first, then show you which route fits.
Frequently asked questions
A record of the goods you send to job workers and get back: challan by challan, what went out, what came back good or rejected, and what is still at the vendor. Section 143(2) of the CGST Act makes you, the principal, responsible for keeping proper accounts of those goods. The law does not prescribe a format.
Inputs must come back, or be supplied from the job worker’s premises, within one year of being sent out, and capital goods within three years. Moulds and dies, jigs and fixtures, and tools have no time limit. The Commissioner can extend the limits by up to one more year for inputs and two more years for capital goods, on sufficient cause.
They are treated as supplied to the job worker on the day they were sent out, under section 143(3) and (4). Rule 45(4) says you declare that supply in GSTR-1 and pay the tax with interest. The register marks those lines “Overdue: deemed supply”.
Half-yearly if your aggregate turnover in the previous financial year was above ₹5 crore, and yearly otherwise, due by the 25th of the month after the period. The register labels each line with its period from the turnover setting at the top.
It is built for Microsoft Excel, and we checked that LibreOffice Calc calculates every formula the same way. Google Sheets has the same functions, but we have not tested the file there.
Yes. The formulas are filled in for 300 rows. For more, copy the last row down and the formulas copy with it.
Sources
The legal points in the file were checked on these pages on 26 October 2026.
Get the file
A record-keeping aid, not tax advice. Check how a particular case is treated with your CA.
Want this in ERPNext instead?
Book a walkthrough. We look at how your plant runs today and tell you plainly what would change.